

Free Consultation
Seattle
Spokane
Bellingham
Mount Vernon
Vancouver
Everett
Uber & Lyft Accidents in Washington: Who Pays?
Content Legally Reviewed By
 Matt Conner
 Determining who pays in an Uber or Lyft accident in Washington relies heavily on the rideshare driver’s app status at the exact time of the collision and which driver caused the crash. While these two factors aren’t the only ones that determine who pays, they give your attorney a starting point when investigating fault and liability.
Under Washington transportation network company (TNC) laws, insurance coverage functions across three distinct periods: the driver’s personal insurance applies when the app is off, rideshare-specific primary coverage with lower liability limits applies while the driver is logged in and waiting for a request, and a primary rideshare $1 million liability policy applies from the moment a ride is accepted until the passenger exits the vehicle. If another driver causes the accident, you may pursue compensation from their personal auto insurance.
When you are injured in an Uber or Lyft crash, insurers may dispute fault or which policy applies. Experienced Seattle uber accident attorneys at Brett McCandlis Brown & Conner can work to identify every applicable insurance policy, help hold negligent parties accountable, and pursue compensation for your losses.
In a typical car crash, you may file insurance claims directly through an at-fault driver’s personal auto policy. A rideshare accident claim in Washington may involve rideshare-specific coverage with limits that change based on what the driver is doing within the rideshare app.
Washington treats rideshare services like Uber and Lyft as transportation network companies (TNCs). State law requires commercial rideshare coverage that protects injured passengers, pedestrians, and third-party motorists when the rideshare driver is at fault.
The driver’s status in the app generally determines which insurer you should pursue for a claim.
When a rideshare driver uses their vehicle for personal errands with the app shut down, neither Uber nor Lyft is required to provide rideshare-specific coverage.
Any accident occurring during this phase is treated as a standard private auto accident. The driver’s personal motor vehicle liability insurance policy applies. If the rideshare driver carries only state-minimum coverage, those limits can quickly be exhausted after severe injuries.
What Coverage Applies When the Driver Is Logged In and Waiting?
When a driver logs into the rideshare app and waits for a dispatch request, they may be looking at GPS screens or circling busy city streets while looking for passengers. They have not yet accepted a passenger, but they are active on the app.
Under those circumstances, Washington requires a primary policy covering rideshare activities with at least the following liability limits:
- Bodily injury coverage of $50,000 per person;
- Total bodily injury coverage of $100,000 per accident; and
- Property damage liability coverage of $30,000 per crash.
The required policy must also address UIM and PIP coverage to the extent that Washington’s insurance statutes require.
Personal automobile policies may exclude coverage for accidents that occur while the driver is logged in or providing a ride unless the driver has a rideshare endorsement or other applicable coverage.
Lyft and Uber accident insurance coverage changes when a driver accepts a passenger ride request and travels toward the pickup point. This period continues while the passenger rides and ends when the passenger exits at their destination.
Washington law requires primary rideshare insurance coverage during this period, including:
- A combined single liability limit of $1,000,000 for death, personal injury, and property damage;
- Underinsured motorist (UIM) coverage of $100,000 per person and $300,000 per accident from the time a passenger enters the vehicle until the passenger exits; and
- Personal injury protection (PIP) coverage to the extent required under state law.
This primary rideshare coverage applies even if the driver’s personal insurer disputes or denies coverage.
Passengers in rideshare vehicles rarely bear any legal responsibility for a crash. During an active trip, rideshare-specific insurance is in place, but the policy that pays depends on who caused the collision and what coverage applies.
If your rideshare driver caused the crash, you can pursue an Uber or Lyft accident claim against the applicable $1 million liability policy.
If another motorist caused the wreck, you would generally pursue a claim against that motorist’s insurance first. If that driver does not have insurance or carries inadequate limits, the rideshare policy’s UIM coverage may apply to an injured passenger.
When a rideshare vehicle collides with your vehicle, compensation depends on fault and what the rideshare driver was doing on the platform:
- The app was offline. You can pursue a claim with the driver’s personal auto insurer if the driver caused the crash.
- The app was online without an accepted ride. You can pursue a claim under the rideshare-specific primary policy with at least 50,000/100,000 bodily injury limits and $30,000 in property damage liability coverage if the rideshare driver is at fault.
- A ride was accepted or active. You may pursue your claim through the applicable $1 million primary liability coverage if the driver is at fault.
Rideshare insurers may dispute app status after an accident. To pursue compensation from the applicable rideshare liability policy, you may need evidence of the driver’s app status at the time of the crash.
Who Pays When a Pedestrian or Cyclist Is Hit?
Pedestrians and bicyclists can suffer serious injuries in traffic collisions. Their liability claims generally follow the same app-status and fault rules that apply to other motorists.
If the driver was offline, the injured person could seek compensation from the driver’s personal auto insurer. If the driver was waiting for a ride request, a limited primary policy may cover that time.
If a rideshare operator strikes a pedestrian while carrying a passenger or driving to a pickup, the $1 million rideshare primary liability policy may apply if the Uber or Lyft driver was at fault.
If a driver leaves the scene of an accident, an injured pedestrian may pursue compensation through their own uninsured motorist coverage or personal injury protection.
Determining who is legally liable in a rideshare accident requires quickly gathering digital and physical evidence. Critical evidence in these claims includes:
- App server records. Digital data logs maintained by Uber or Lyft confirm the driver’s exact app status at the time of the crash.
- Police traffic collision reports. Official crash reports written by local law enforcement officers or the Washington State Patrol document any citations issued and crash details.
- Video footage. Video recordings from dashcams, intersection traffic cameras, and local business surveillance cameras provide visual evidence of what happened.
- Accident scene photographs. Images showing vehicle damage, skid marks, road hazards, traffic signals, and bodily injuries provide information for crash reconstruction.
- Electronic data recorder downloads. On-board vehicle data may show speed, braking effort, and steering inputs before a collision.
Rideshare corporations may not readily turn over internal data logs. An attorney can send a formal preservation letter requesting that the rideshare platform retain essential electronic files.
What Steps Should You Take After an Uber or Lyft Crash?
The steps you take following a rideshare collision can affect your health and legal rights.
- Call 911 immediately. Request law enforcement and paramedics at the crash scene so police can create an official report and EMS can evaluate injuries.
- Save digital app records. If you were a passenger, take screenshots of your rideshare application showing the driver’s name, vehicle make and model, trip receipt, and travel route.
- Take detailed photographs. Take photos and videos of vehicle damage, road signage, debris, and any physical cuts or bruising.
- Collect contact information. Exchange contact and insurance details with all involved drivers, and collect names and phone numbers from neutral eyewitnesses.
- Get a complete medical examination. See a physician at an emergency department or urgent care facility right away, because shock and adrenaline can mask soft-tissue trauma and internal injuries.
- Report the accident to the rideshare company. If you were a passenger, use the app to report the rideshare accident in Washington by selecting the trip you were on and tapping the button indicating there was a crash. Provide the company with the necessary details, but do not assume fault or liability.
- Avoid giving recorded statements to insurance adjusters. Commercial adjusters represent the corporate rideshare company’s financial interests, so avoid giving them detailed information until you get legal advice.
Your attorney can also get an independent investigation started as soon as possible.
FAQs About Who Pays In an Uber or Lyft Accident
Who pays in a rideshare accident generally depends on whether the rideshare driver is at fault and the app’s status. If the rideshare driver was actively transporting a rider or en route to a pickup, the primary rideshare liability policy may cover compensation for your damages. If the driver is offline, you may pursue the driver’s personal policy for compensation.
If a third-party driver caused the accident, you may pursue a claim against their auto insurance. The primary rideshare policy also provides lower liability coverage when the driver is online but hasn’t accepted a ride. UIM coverage may apply when another driver lacks sufficient insurance, depending on the coverage period.
Can You File a Lawsuit Directly Against Uber or Lyft?
You generally file an insurance claim under the applicable rideshare liability policy rather than suing the corporation directly. Because drivers are independent contractors, direct lawsuits against the company generally require showing independent corporate negligence, such as negligent hiring, inadequate driver background checks, or failing to remove an unsafe driver.
If a third-party driver causes the collision, you can pursue that driver’s personal auto insurance for compensation for your injuries. If that motorist carries insufficient insurance limits or has no auto insurance at all, the rideshare policy’s underinsured motorist (UIM) coverage may apply if you were a passenger in the Uber or Lyft when the crash occurred.
No, the $1 million liability coverage does not apply at all times. This coverage generally applies only when the driver is en route to pick up a passenger and when a passenger is riding. When a driver is waiting for a dispatch, the primary rideshare liability policy provides lower liability limits.
Medical bills, lost wages, and uncooperative corporate insurance adjusters can leave you frustrated and uncertain about your future. You do not have to handle multi-billion-dollar transportation network companies on your own.
At Brett McCandlis Brown & Conner, our attorneys have represented injured individuals across Washington for more than 40 years. We know how to secure app data, handle commercial adjusters, and prepare cases for trial when insurance carriers refuse to negotiate fairly.
We handle cases on a contingency-fee basis, meaning you pay no legal fees unless we win compensation for your claim. Contact Brett McCandlis Brown & Conner today to schedule your free consultation.
Legal References Used to Inform This Page
To ensure the accuracy and clarity of this page, we referenced official legal and other resources during the content development process:
About the Author
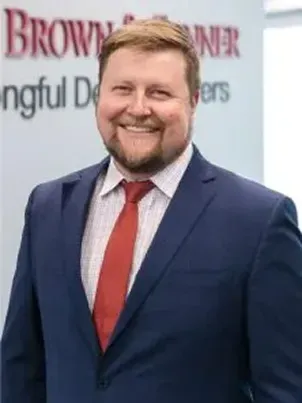
Matt Conner
Matt Conner has a proven track record of success. Following his graduation from Willamette University with a double major in mathematics and economics, Matt worked as an economist for the Office of Economic Analysis for the State of Oregon before moving onto working in mortgage banking and real estate. Although Matt would move on to law school shortly thereafter, his experience in the financial sector has provided him with valuable experience in how to achieve maximum compensation for his clients.
October 28, 2026
October 28, 2026
October 28, 2026
October 28, 2026
October 28, 2026